

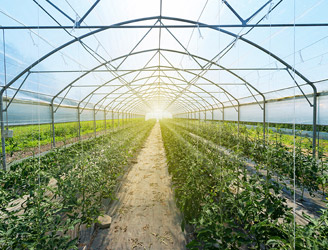


Hydroponic and aquaponic growers can look very different from traditional greenhouse or nursery operations.
Their businesses may depend on interconnected equipment, environmental controls and growing systems that are critical to maintaining production. They may also operate alongside more traditional greenhouse, nursery, retail or distribution operations.
For brokers, that makes understanding how the business grows and what the operation depends on an important starting point.
It also makes specialized horticulture insurance worth a closer look.
GrowPro by NIP Group considers qualifying hydroponic and aquaponic operations as part of its broader horticultural appetite, with coverage and expertise designed around the needs of growing businesses.
Start with how the operation grows
Rather than simply asking, “Is this a greenhouse?”, start with a different question:
How does this operation actually produce and protect what it grows?
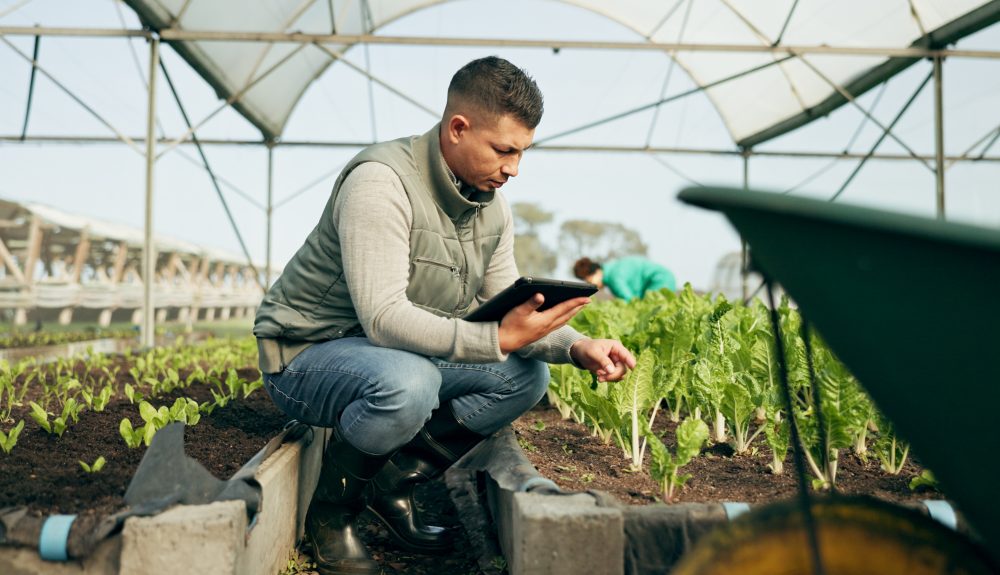
Hydroponic operations grow without traditional soil-based production, while aquaponic operations can combine plant production with aquatic systems.
Depending on the business, production may rely on systems such as:
- Water circulation, pumps and filtration
- Lighting and environmental controls
- Nutrient delivery
- Monitoring equipment
- Backup power
- Other automated production equipment
These systems may be central to maintaining the growing environment. If something changes or stops working, the impact can extend beyond the equipment itself.
Brokers don’t need to conduct an engineering review. But understanding what the operation depends on helps tell a more complete account story.
Specialized operations can call for specialized coverage
The equipment and systems are only part of the picture.
GrowPro brings together horticulture-specific expertise and coverage relevant to growing operations, including Growing Stock Endorsement, Equipment Breakdown Coverage, Cladding Coverage and consideration of qualifying hydroponic and aquaponic operations.
For a business dependent on pumps, controls and environmental systems, equipment breakdown can be an important part of the coverage conversation.
Growing stock creates another consideration. A loss affecting the growing environment may involve more than repairing damaged property or equipment, making it important to understand how the operation and its coverage work together.
Coverage ultimately depends on the specific account and applicable policy terms, conditions, exclusions and endorsements.
Look at the whole horticulture operation
A hydroponic or aquaponic grower may not operate under a single, simple label.
The business could also include greenhouse growing, nursery production, retail garden center sales, wholesale distribution, delivery operations or multiple growing locations.
GrowPro considers qualifying greenhouse growers, nurseries, garden centers and hydroponic and aquaponic operations.
That means brokers don’t need to decide exactly where a mixed operation fits before starting the conversation.
Instead, help us understand the business:
What do they grow? How do they grow it? What systems does production depend on? And how has the operation changed?
GrowPro has expanded — and the account may have changed, too
A horticulture operation can look very different from one renewal to the next.
New automation. Additional growing space. More equipment. New locations. Higher property values. Changes to the way the business produces or distributes its product.
At the same time, GrowPro has recently expanded its capacity and underwriting flexibility, increasing our ability to consider larger and more complex qualifying horticulture risks.
That creates a reason to take another look at both new opportunities and accounts that may not have fit GrowPro previously.
If you haven’t discussed an account with us recently, the operation — and GrowPro — may look different today.
What should brokers bring to the conversation?
You don’t need every underwriting detail before reaching out.
A useful initial overview can include the primary growing operation, location information, major production systems, approximate property and equipment values, recent expansion or operational changes, and the upcoming effective date.
From there, the GrowPro team can help identify what additional information may be useful to evaluate the opportunity.
When to consider GrowPro
Growers face a complex mix of risks that aren’t fully addressed by general commercial products. Property concentrations, seasonal inventory swings, high-value equipment, and unique structural considerations (such as greenhouse glazing or controlled lighting systems) require underwriting that understands the industry.
GrowPro provides brokers with:
- Purpose-built protection for nurseries, greenhouse growers, and garden centers
- Expert underwriting and risk control, grounded in deep industry experience
- Competitive structure and flexibility to support diverse growing operations
- Support for advanced agriculture, such as hydroponic or aquaponic facilities, when more technical expertise is needed
Whether you’re working with a small retail grower or a sophisticated propagation facility, having access to a specialized program allows you to tailor coverage rather than adapt a generalist solution.
Download our Broker Appetite Guide – NIP Group, or https://nipgroup.com/growpro to get started. Our team is ready to help you win accounts that others can’t.